
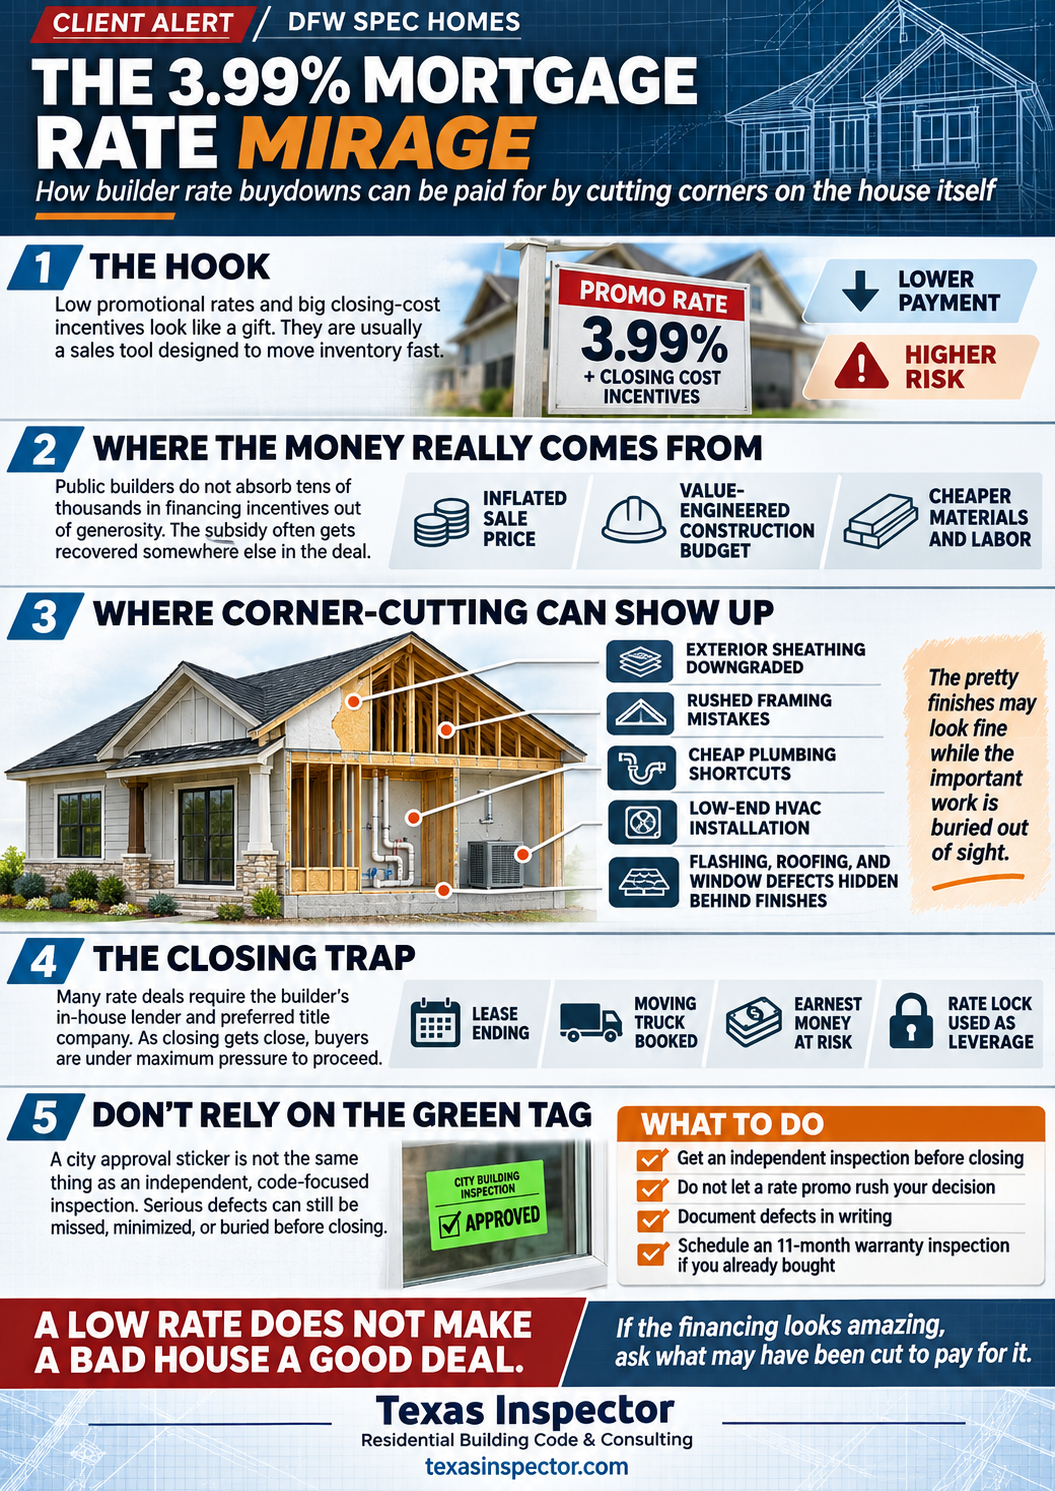
Drive down any highway in Dallas-Fort Worth right now and you will be blinded by neon billboards from Celina to Midlothian screaming the same fairy tale. Production builders are dangling 3.99 percent mortgage rates and thirty-thousand-dollar closing cost giveaways on move-in-ready spec homes like candy from a windowless van. To a Texas family exhausted by high interest rates, it looks like a miracle. To a code-certified inspector who actually crawls through the attics and framing of these tract-home masterpieces every week, it looks like a hostage situation with a low monthly payment.
Let us get one thing straight right out of the gate: publicly traded homebuilders are not Mother Teresa with a nail gun. They do not love you, they do not care about your family’s financial future, and they sure as hell do not eat forty thousand dollars in financing subsidies out of the goodness of their corporate hearts. They answer to Wall Street sociopaths who demand thirty-percent gross margins every single quarter. When a builder spends thirty-five grand buying down your interest rate through their captive mortgage subsidiary, they keep the home’s sticker price artificially inflated to prop up neighborhood comps, and then they quietly loot that thirty-five grand directly out of the sticks, bricks, and labor sitting on your lot.
The Spreadsheet Heist Behind the Drywall
Before a single shovel hits the North Texas black clay on a 2026 spec lot, a twenty-six-year-old MBA in the builder’s purchasing department opens an Excel spreadsheet and starts playing a game called value engineering. That is corporate-speak for figuring out how much structural integrity they can strip out of your house before it collapses during the walkthrough. If the marketing department needs forty thousand dollars per lot in financing shiny-objects to lure buyers into the sales office, the construction budget gets taken behind the woodshed. Naturally, you will never notice these cuts while sipping complimentary bottled water with the sales rep, because the builder still installs the shiny quartz countertops, the trendy matte-black faucets, and the giant farm sink that makes your spouse swoon on Zillow.
The actual butchery happens behind the drywall where you aren’t supposed to look. On late-2026 incentive specs across DFW, builders have largely abandoned real structural exterior sheathing in favor of glorified structural cardboard that loses a fistfight with a wet paper towel, let alone a seventy-mile-per-hour Texas straight-line wind. In the plumbing rough-in, clean PEX manifold systems have been ditched for chaotic spaghetti webs of cheap plastic fittings buried under concrete and dragged over sharp attic trusses. And for your heating and cooling, they toss in the cheapest single-stage condenser that fell off the back of a supply truck, strangle the flex ducts over ceiling joists like a python, and leave you wondering why your brand-new house smells like a locker room by July.
The Thirty-Day Closing Blitz and Pickup-Truck Labor
Paying for your shiny 3.99 percent interest rate takes more than buying garbage materials; it requires turning the build schedule into a caffeinated demolition derby. Unsold spec homes cost the builder daily interest on their credit lines, which means a sitting inventory home makes division presidents break out in hives. The second you sign a purchase contract tied to a rate promo, the corporate mandate comes down from on high: close that house before the end of the fiscal quarter, even if the paint is still wet and half the roof isn’t nailed down.
To hit that delusional timeline, construction managers stop hiring skilled trade contractors who actually know how to read the International Residential Code. Instead, they hire whichever crew pulls into the subdivision with a beat-up pickup truck, a compressor, and a pulse. When I walk into these incentive builds for pre-drywall or final inspections, it is an absolute circus of incompetence. Plumbers take reciprocating saws and hack through load-bearing studs like beavers on a bender, framers forget that hurricane ties and shear-wall nails exist, roofers blast nails straight through Class-nothing shingles at ninety pounds per square inch, and window crews slap vinyl frames into rough openings without a single strip of sill-pan flashing. Then the city inspector—or worse, the builder’s pet third-party rubber-stamper—slows his truck down to twelve miles per hour, waves a clipboard out the window, and passes the house so the drywall crew can bury the evidence by sunrise.
The Captive Lender Shakedown
The real chef’s kiss of the rate-buydown grift happens forty-eight hours before closing. Every single one of those promotional interest rates forces you to use the builder’s wholly owned, in-house mortgage company and preferred title mill. By the time you are a week out from closing, your apartment lease is up, the moving van is packed, and the builder owns your soul. If you dare to walk away, they keep your earnest money and your precious 3.99 percent rate evaporates into the Texas humidity.
That is the exact moment the builder’s sales team drops the velvet glove and brings out the brass knuckles. When you hire a real inspector who hands them a forty-page forensic report detailing rotted sheathing, disconnected flues, and unbolted framing, the builder’s construction manager doesn’t apologize—he laughs at you. They will point at their worthless municipal green tag, tell you their subcontractors are the best in the business, refuse to fix a damn thing, and threaten to void your rate lock if you are not sitting at the title company table by Friday at four o’clock. They are betting the house—literally your house—that you are too desperate for a four-hundred-dollar monthly payment savings to fight back over fifty thousand dollars of hidden structural rot.
Stop Letting the Fox Finance the Henhouse
Taking a builder’s money to buy down your interest rate is great, provided you understand that you are dealing with a casino that rigs the roulette wheel. If you let a shiny financing flyer talk you out of a ruthless, code-certified inspection, you aren’t getting a deal; you are just financing your future repair bills at 3.99 percent. Before you sign on the dotted line for a discounted DFW spec home—or before your eleven-month warranty clock runs out on the incentive trap you bought last year—contact Aaron D. Miller at Texas Inspector so we can find out exactly which parts of your house the builder sold off to pay for your billboard rate.


